Key facts: Insurance adjusters
- Most homeowners policies require prompt notice and reasonable steps to protect the property from further damage.
- Standard homeowners policies usually exclude flood from outside water; flood cover is a separate policy.
- California's Fair Claims Settlement Practices Regulations set timelines insurers must follow for acknowledging and handling claims.
- The California Department of Insurance offers a consumer hotline and complaint process if a claim stalls.
The adjuster's job
What the adjuster is trying to find out
An adjuster works for the insurer (unless you hire a public adjuster, who works for you). Their questions follow the policy: what caused the water, when it started, whether the cause is covered, how far the damage spread, and what it takes to repair it. Two details often decide a claim: whether the water was sudden or gradual, and whether it came from inside the house or from outside.
A burst supply line found the same day is a sudden internal loss. A shower pan that leaked for months is gradual. River or street water entering a Beach Colony home is flood. Each is treated differently under most policies, so the cause needs to be clear and documented.
Preparation
What to do before the adjuster arrives
- 1
Give notice promptly
Call your insurer or agent the same day if you can. Write down the claim number and the name of everyone you speak to.
- 2
Protect the property
Stop the water and start mitigation. Policies expect reasonable steps to prevent further damage, and that mitigation work is usually part of the claim.
- 3
Photograph and video everything
Every room, the source, the water line, damaged contents, and the exterior if a storm was involved, before anything is moved or removed.
- 4
Keep what is removed, or photograph it
Ask whether the insurer wants damaged materials kept. If not, photograph them with a tape measure or meter reading in the frame.
- 5
Start a contents list
Room by room: item, approximate age, where it was bought, and photos. Receipts help but are not always required.
- 6
Keep every receipt
Hotel stays, meals out, emergency purchases and equipment rental may be claimable under additional living expense cover.
Documentation
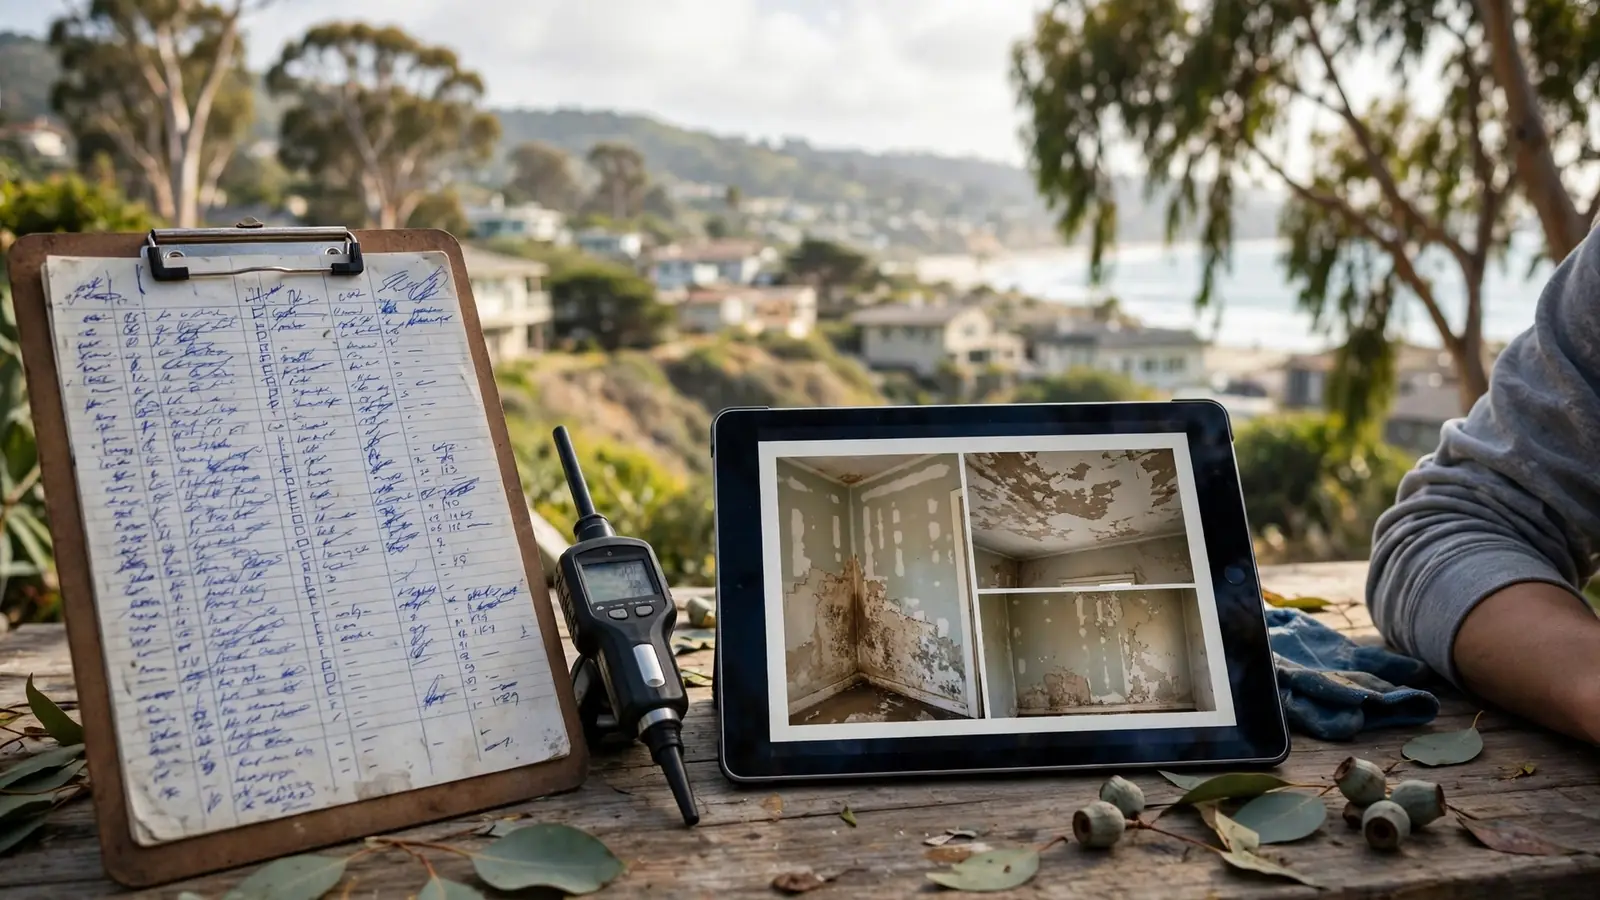
Records that help a water damage claim
| Record | Why it matters |
|---|---|
| Photos and video before cleanup | Show the extent and the cause as they were |
| Plumber or roofer report | Explains the cause and whether it was sudden |
| Moisture map and drying log | Shows where water went and that the structure was dried |
| List of removed materials | Explains what was taken out and why |
| Contents inventory | Supports the personal property part of the claim |
| Receipts for living expenses | Supports additional living expense claims |
| Notes of calls and visits | Keeps the timeline clear |
On the day
During the adjuster's visit
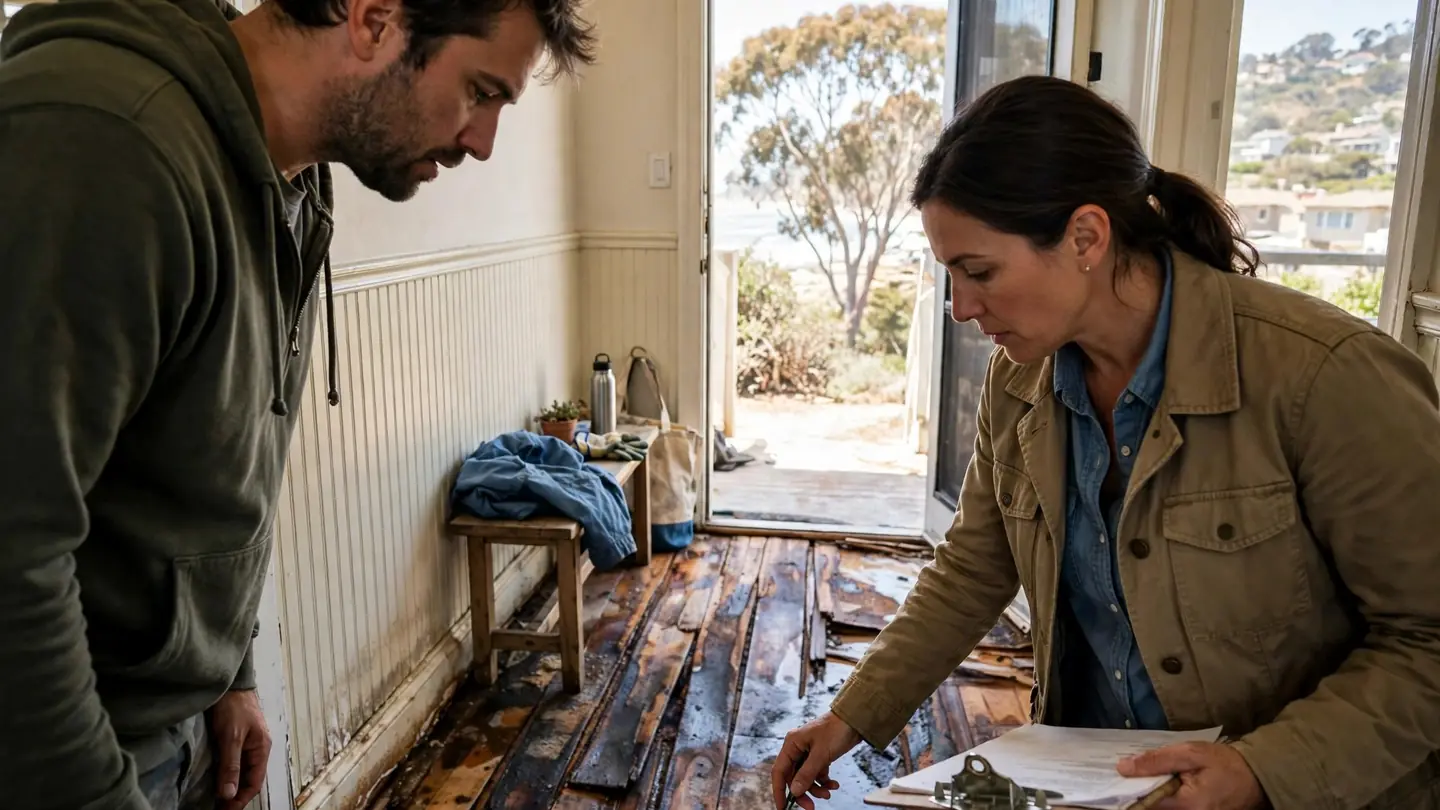
Walk the adjuster through the home in the order the water travelled, starting at the source. Show the photos you took before cleanup and the contractor's moisture map, and point out anything that is no longer visible, such as materials already removed. If the contractor can be there, they can explain the readings and why each removal was needed.
Ask what happens next and when, who your contact will be, and what else they need from you. Take notes. If the adjuster gives a scope of repairs, compare it with the contractor's; differences are common and are usually resolved by sharing records rather than by argument.
Flood
Flood claims are different
If water came from outside, such as the San Dieguito River, a flooded street or ocean overtopping, your homeowners policy probably excludes it, and a flood policy applies if you have one. Many homes in mapped flood zones near the river carry flood insurance through the National Flood Insurance Program or a private insurer. [2] Flood policies have their own rules for what is covered, especially in lower levels and for contents, and their own deadlines for proof of loss.
When a storm causes both outside flooding and an inside leak, keep the two separate in your notes and photos. A sewer backup may fall under a homeowners endorsement rather than flood. The FloodSmart site explains how NFIP claims work.
Shared buildings
Condo and HOA claims
In a condo, at least two policies are usually involved: the HOA's master policy and your unit policy. The CC&Rs say which covers what, and the master policy may carry a large deductible that the CC&Rs allocate in some way. If water came from a neighbor's unit, your insurer may pay your claim and then recover from the neighbor's insurer. Report the loss to your insurer and the HOA, and share the contractor's records for your unit.
The contractor's role
Working with your restoration contractor
The restoration contractor documents the moisture, the removals and the drying, and that record is often what the adjuster relies on. Ask for copies of the moisture map, daily readings, photos and the final drying log. Most contractors are used to sharing these with adjusters directly if you authorise it.
You choose the contractor; your insurer may suggest one but cannot generally require you to use it. Before work starts, check the contractor's licence on the CSLB website and get the scope in writing.
FAQ
Adjuster questions
Do I have to wait for the adjuster before drying starts?
Usually not. Document the damage and begin mitigation; waiting lets damage grow. Tell your insurer what you are doing.
What if the adjuster says the leak was gradual?
Ask for the reasoning in writing and share any plumber report or evidence that the leak was sudden. You can contact the Department of Insurance if you disagree.
Can I throw away damaged items?
Photograph and list them first, and ask your insurer whether they want anything kept for inspection.
Is a public adjuster worth it?
For large or complicated losses some owners find one helpful. They are licensed in California and are paid under a written contract, so read it carefully before signing.
Sources and citations
- [1]California Department of Insurance
- [2]FloodSmart (National Flood Insurance Program)
- [3]FloodSmart (FEMA): Flood zones and maps
- [4]Contractors State License Board (CSLB)
- [5]IICRC S500 Standard for Professional Water Damage Restoration
- [6]California Code of Regulations: Fair Claims Settlement Practices Regulations (CDI)